

Entering the European market for speciality coffee
Selling specialty coffee in Europe requires meeting strict EU rules, which apply to food safety, hygiene, labelling, and limits for pesticides and mycotoxins, as well as proper packaging and payment terms. Sustainability regulation is becoming stricter. Coffee quality is often judged using the older Q grading system, while the newer Coffee Value Assessment is slowly gaining ground. The specialty coffee market is highly competitive, with different quality segments and sales channels. Success depends on clear positioning, quality and strong buyer relationships.
Contents of this page
1. What requirements and certifications must specialty coffee meet to be allowed on the European market?
The European Union (EU) is a single market. The EU sets most of the rules for coffee imports. These rules apply to all member states. EU legislation generally matters more to producing-country exporters than country-specific legislation. Next to EU regulations, there are also country-specific regulations. Some European countries are not part of the EU, for example Switzerland and the UK. For non-EU countries EU regulations do not apply, but most of these countries have requirements that are very similar to those of the EU.
There are no specific legal requirements for specialty coffee. The legal requirements that apply to conventional coffee also apply to specialty coffee. In this section, we focus on requirements for exporting specialty coffee to the EU:
- Mandatory requirements (like food safety and hygiene);
- Additional company requirements (to succeed in the market);
- Niche market requirements (like certification).
The mandatory requirements, additional requirements and the requirements for niche markets are described below.
What are mandatory requirements?
Most mandatory requirements are legal requirements that come from the EU, pertaining to food safety, labelling, payment, sustainability and quality. Most requirements are equal for all European markets.
Requirements for food safety and hygiene
Exporters must follow the EU food safety laws applicable to coffee. These rules deal mainly with food safety, with traceability and hygiene as top priorities. Special attention should be given to specific sources of contamination of pesticides and mycotoxins/mould, particularly Ochratoxin-A (OTA).
Generally, your buyer will ask for a phytosanitary certificate. This certificate is provided by your country's plant protection authorities. A phytosanitary certificate guarantees that coffee is:
- Properly inspected;
- Free from pests;
- Meets all plant health requirements.
Labelling requirements
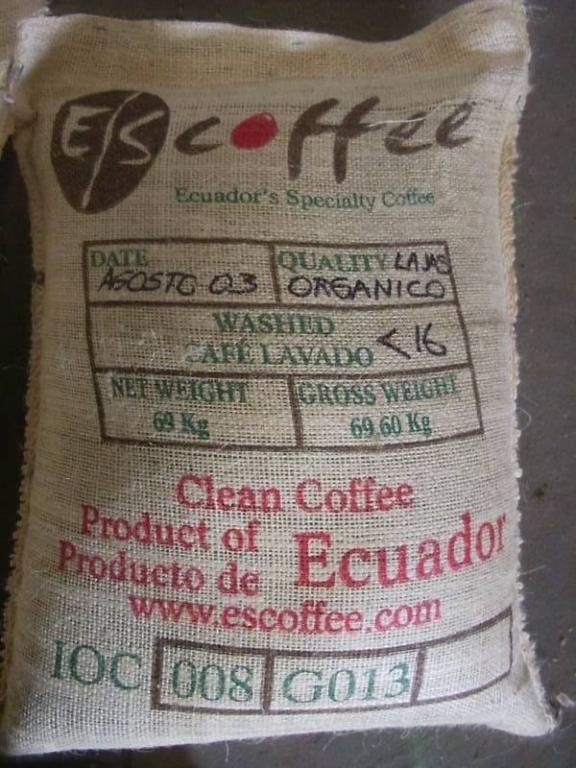
Labels on green coffee exported to Europe should be written in English and should include the following information to ensure the traceability of individual batches:
- Product name;
- International Coffee Organisation (ICO) identification code;
- Country of origin;
- Grade;
- Net weight in kg;
- For certified coffee: name and code of the inspection body and certification number.
Figure 1: Example of green coffee labelling
Source: Escoffee
Payment and delivery terms
You usually get paid for your coffee when the buyer receives it, or within 30–45 days, depending on your contractual terms. Cash Against Documents is the most common payment method when exporting coffee to Europe. You provide documents proving shipment, such as a bill of lading or invoice, and get paid in return. This ensures you receive payment for your goods.
It is crucial to examine these terms carefully. Generally, you will get paid sooner if you sell your coffee to a trading company than if you sell it directly to a coffee roaster.
Packaging requirements
Green coffee beans are traditionally shipped in woven bags made from jute or hessian natural fibre. Jute bags are robust. Most specialty coffee suppliers also use other materials inside jute bags to protect the beans. These materials have added value over traditional packaging. They preserve bean quality, prevent post-harvest loss, reduce solid waste, reduce farmers' net carbon footprint, and facilitate chemical-free storage. Popular brands are GrainPro, Ecotact and Videplast.
Quality requirements
Green coffee is graded and classified for quality before export. There is no universal grading and classification system for coffee. The Specialty Coffee Association's (SCA) coffee standards are the most used grading scale. While the SCA sets the leading standards, some producing countries have their own grading systems.
Based on SCA standards, the valuation of specialty coffee is done via the Coffee Value Assessment (CVA). The CVA, formally adopted by the SCA in November 2024, replaces the previous 100-point cupping form and is now the global standard for specialty coffee assessment. The CVA gathers four types of information:
- Physical bean quality (such as colour, physical defects, moisture, bean size);
- Sensory/descriptive traits (aroma, flavour, body, acidity, aftertaste);
- Affective assessment (impression of quality, defects and uniformity);
- Extrinsic factors (variety, processing, origin, sustainability).
Figure 2: Coffee assessment in Rwanda
Source: Ethos Agriculture, 2023
On 1 October 2025, the SCA took over the Q Grader program from the Coffee Quality Institute (CQI), renaming it the 'Evolved Q Grader Program' and aligning it with its Coffee Value Assessment (CVA) system. This change has created concern among many Q Graders and instructors, especially around higher costs, unclear transition plans, and the need to pay again to stay certified under the new system. Critics worry that the shift centralises control, could weaken the value of existing Q credentials, and may make certification even less accessible for producers and professionals in producing countries, deepening inequality in coffee education. While some welcome the broader view of coffee value, many are calling for clearer links to pricing, fairer access, and stronger support during the transition.
If you export speciality coffee, it is important for buyers to know the cupping score of your coffee. The cupping score is relevant information to document when exporting your coffee. The score can also provide feedback to producers. This allows everyone in the supply chain to know the coffee's quality. Cupping evaluations are done by professionals called graders. The CVA includes a score calculator that converts assessments to the legacy 100-point format, so buyers familiar with the old grading system can still understand the results during the transition period.
You can read much more about the valuation of specialty coffee on the SCA website. You can also inform yourself on the new Coffee Value Assessment system by watching the video below.
Figure 3: Theory of the SCA Coffee Value Assessment
Source: SCA, 2024
Sustainability requirements become stricter
In recent years, the EU has led a global change by passing strong new sustainability regulations. This set of EU regulations builds upon the international soft laws such as the UN Guiding Principles on Business and Human Rights and the OECD Guidelines for Multinational Enterprises on Responsible Business Conduct. EU regulations require coffee companies to check for human rights and environmental risks in their supply chains.
The European Green Deal (EGD) is the EU's response to the global climate emergency. The EGD is a package of policies that define Europe's strategy to reach net-zero emissions and become a resource-efficient economy by 2050. The EGD's four instruments are:
- European Deforestation Regulation (EUDR)
- European Corporate Sustainability Due Diligence Directive (CSDDD)
- Forced Labour Regulation
- Empowering Consumers for the Green Transition (EmpCo)
The European Deforestation Regulation prohibits coffee that leads to deforestation
As part of the European Green Deal, the EU has developed the Regulation on Deforestation-free Products (EUDR). The EUDR requires companies to prove that the products they import do not come from deforested land and have not contributed to forest degradation. Only deforestation-free products can be placed on the EU market.
In December 2024, the EU postponed implementation by a year, to 30 December 2025. In November 2025, the EU decided to postpone the regulation again, to 30 December 2026. Micro and small enterprises are granted an additional six months. This law makes traceability and technology crucial for exports to the EU market, and will have implications for the coffee-producing industry. The EU provides a guidance document and an information sheet that address frequently asked questions.
Certification can be one of the tools that help demonstrate that your company complies with the EUDR. This may involve certification schemes with strict environmental criteria promoting sustainable farming practices, like organic and Rainforest Alliance. However, while providing relevant infrastructure, certification alone is not sufficient.
The CSDDD increases requirements for traceability and human rights
Under the new CSDDD regulations, European corporations must improve their sustainability performance across their global supply chains. They must also prevent damaging effects on human rights and the environment. Businesses are required to take the following actions:
- Integrating due diligence into their policies;
- Identifying actual or potential adverse impacts;
- Preventing and mitigating potential adverse impacts;
- Establishing and maintaining a complaints procedure;
- Monitoring the effectiveness of their due diligence policy and measures;
- Publicly communicating on due diligence.
The directive forces European companies to take responsibility for their full supply chain, so it may force your buyers to ask for proof that you act socially and environmentally sustainably. It will apply from 26 July 2029.
The Forced Labour Regulation bans coffee produced with forced labour from the European market
The objective of the Forced Labour Regulation is to ban the production or export of any product made using forced labour.
Based on risk assessments, companies based in the EU will be forced to ensure that no forced labour occurs within their supply chain. In April 2024, the EU Parliament gave its final approval of the legislation. Companies should be prepared to follow the regulation's requirements from 14 December 2027. Non-compliant European companies will be fined.
Companies must audit their supply chains for exploitative labour practices, since any link to forced labour triggers market exclusion and reputational damage. Coffee is explicitly recognised as a high-risk commodity under the regulation. The full effect of the Forced Labour Regulation on exporting companies is still unclear, but it will mean that European buyers will require more information from their suppliers.
What additional requirements and certifications do buyers often have?
Some buyers may demand extra food safety requirements for processing or additional quality standards.
Additional food safety requirements
Some buyers in Europe may request extra food safety guarantees from you. These usually cover production and handling processes. For example:
- Implementation of good agricultural practices (GAP). The main standard for good agricultural practices is GLOBALG.A.P., a voluntary standard for certification showing that products are traceable and safe. Certification organisations often incorporate GAP into their standards, for example Rainforest Alliance.
- Implementation of regular checking of residue levels. Ochratoxin-A (OTA), polyaromatic hydrocarbons (PAHs) and glyphosate contamination should be prevented and checked. It is recommended to get certificates that show periodical analysis of the coffee, which includes conducting periodical checks. This is preferably done from an EU-accredited laboratory, like eurofins or TUV SUD.
- Ensure high traceability. For many European specialty coffee buyers, this is crucial. European consumers want to know where their coffee comes from.
Additional sustainability requirements
European traders and small-scale roasters in the specialty segment work with ethical and sustainable sourcing. Direct contact with producers, transparency, and promoting sustainable practices are important values to them. Importers that have high corporate social responsibility (CSR) standards include Trabocca and This Side Up Coffees (Netherlands), Ethiquable (Belgium), and GEPA and El Puente (Germany). These importing companies work on projects with coffee-producing cooperatives in the countries of origin.
How you connect with your buyers is important for building a long-term relationship. European buyers value effective communication with producers and appreciate a prompt response to phone calls and emails. This means excellent communication about delivery terms and quality.
If you cannot meet all delivery requirements, informing your buyers in time is crucial. This offers them the opportunity to respond and take measures. An example is ordering more volume via another buyer: although this is not attractive, the consequences of no communication are worse. Insufficient or late communication are often the main reason for shifting to other suppliers. European communication standards are generally a lot higher than you expect.
What are the requirements for niche markets?
The European market has special requirements for organic coffee.
Organic certification
Exporting organic coffee comes with extra requirements. To market your coffee as organic in the European market, it must meet EU regulations for organic production and labelling. Since 1 January 2025, Regulation (EC) 2018/848 applies to exporters out of the EU as well. Under the new rules, lot testing is intensified and coffee cannot be shipped or invoiced while awaiting test outcomes. Another important change is that only cooperatives or legally recognised producer organisations can become certified.
Organic coffee is checked at the EU border. To import organic coffee to the EU, the shipment needs to include an electronic certificate of inspection (e-COI). The certificate should be set up in the Trade Control and Expert System (TRACES). It must be signed by a control authority in your country before the shipment leaves the country. If you want to export to countries outside of the EU, check the requirements from that specific country. For example, Switzerland has its own Swiss Organic Law, and the UK has Organic Products Regulations 2009.
Next to the EU standards, most companies and third-party certification schemes have additional requirements. It is important to check the requirements asked for on the standard's website. For instance, this Naturland handout compares Naturland's additional requirements with the EU Organic regulation.
A certifier must audit your growing and processing facilities to issue organic certification. The EU provides a list of recognised control bodies and authorities. This way, you are always assured of working with an accredited certifier. After auditing and receiving organic certification, your products can use the EU organic logo.
Tips:
- Find buyers that match your business philosophy and export capacities in terms of quality, volume and certifications. For more tips on finding the right buyer for you, see our study on finding European coffee buyers. Also, read the Specialty Coffee Transaction Guide for more information on how to do business.
- Invest in long-term relationships. Whether you are working through importers or roasters, you must establish strategic and sustainable relationships with them. This will help you manage market risks, improve the quality of your product, and reach a fair quality-price balance. Read our tips on how to do business with European coffee buyers. The article provides insights into what your European coffee buyer values in the trading process.
- Inform yourself on artificial intelligence (AI) solutions to improve the process of coffee grading. These are promising to enhance the efficiency of the grading process. Programmes already available in the market include Demetria, Csmart, Agrivero, ProfilePrint and Avercasso. You can read more about this on the Digital Coffee Future website.
- Some of the EU regulations described in this section, which are not yet in force, are constantly debated and changing. It is important to check the current status. Check the European Commission website on the EUDR, the Forced Labour Regulation and the CSDDD. For example, in May 2026 a simplification to the EUDR was proposed.
2. Through which channels can you get specialty coffee on the European market?
Specialty coffee is sold in the high-end or upper-end market. It flows into the European market via specialised buyers and mainstream traders. However, the specialty coffee market offers opportunities for direct trade. This can often lead to higher margins.
How is the end market segmented?
Speciality coffee is the higher part of the market. These are the coffees with a higher quality and price. Specialty coffee often stands out from the conventional coffee market in terms of quality, storytelling and traceability.
Also, pricing of specialty coffee is different from conventional coffee, and varies across the specialty segments. Conventional Arabica coffee largely follows the C price, the global benchmark established through trading in standardised Arabica futures contracts. Specialty coffee does not always closely follow the C market. Unique flavour profiles, micro-lot scarcity, and direct trade relationships often push prices beyond commodity benchmarks. In longer-term specialty relationships, prices are typically negotiated bilaterally and shaped more by shared values and quality considerations than by exchange-based reference prices.
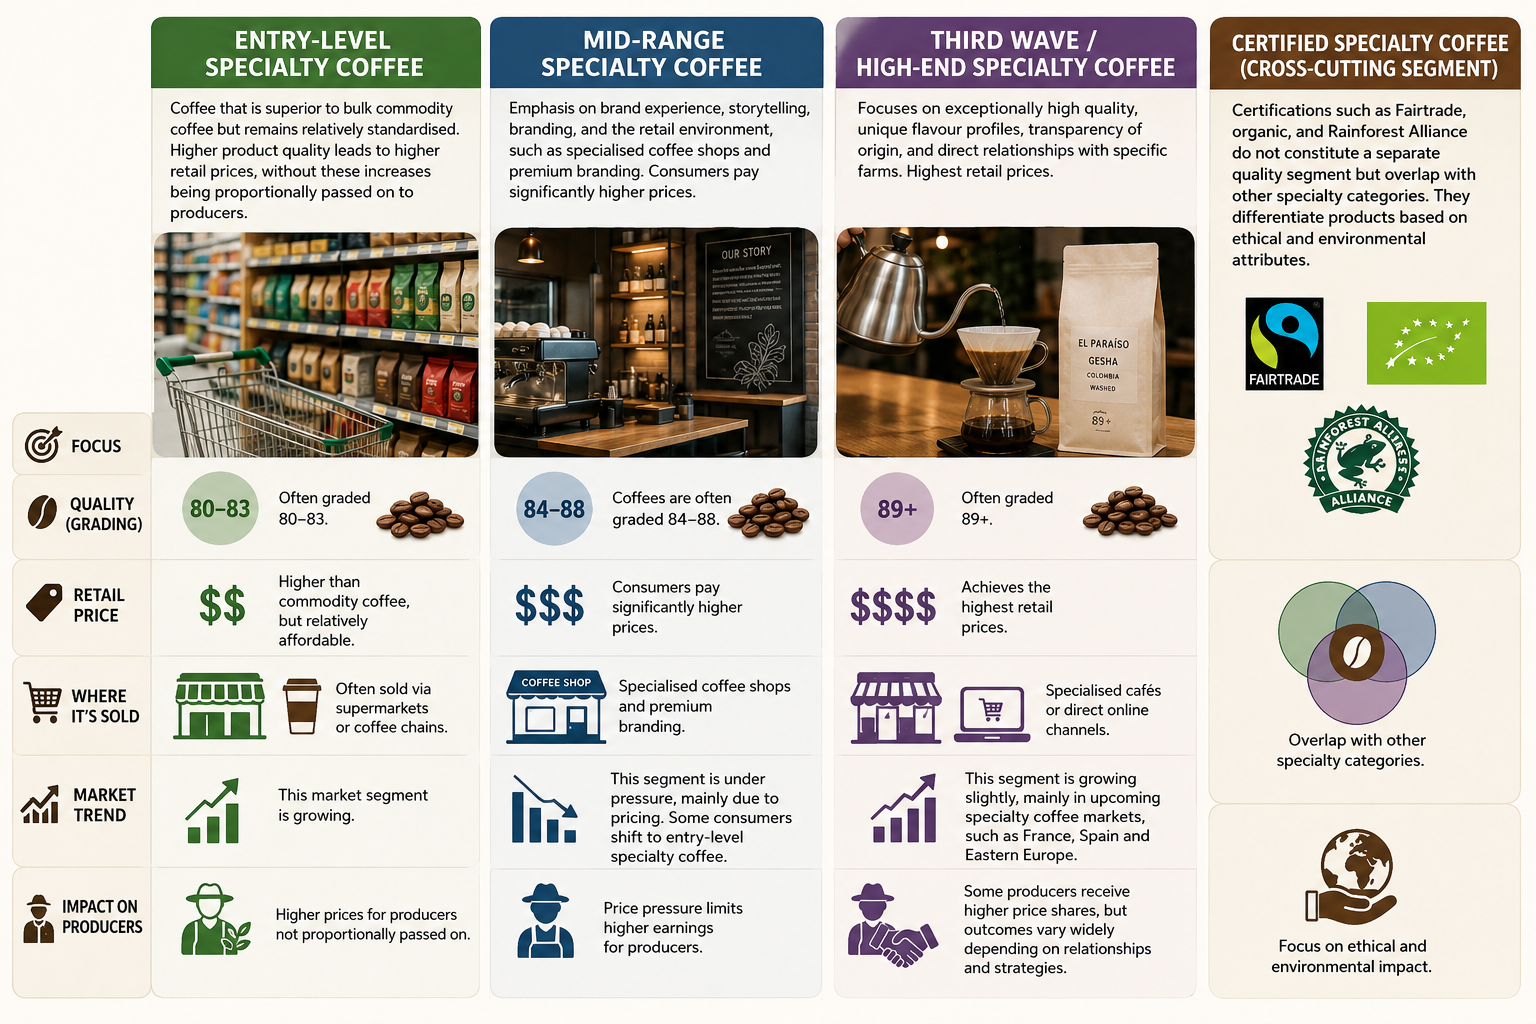
Although the specialty coffee is generally seen as one segment, there are major differences among specialty coffee segments. Overall, the specialty coffee segment can be broken down into four subsegments. A good source for getting better insight into the specialty coffee prices, including prices across different market segments, is the Specialty Coffee Transaction Guide. The guide provides an insight on how specialty coffees of a certain grading relate to the C price.
Entry-level specialty coffee (cupping scores 80–83)
This segment includes coffee that is still largely sold through commercial channels, but where quality is explicitly recognised and rewarded. The coffee is superior to bulk commodity coffee but remains relatively standardised. It is often sold via supermarkets or coffee chains. Most specialty coffee falls into this segment, where higher product quality leads to higher retail prices, without these increases being proportionally passed on to producers. These coffees in this growing market segment are often graded 80-83.
Mid-range specialty coffee (cupping scores 84-88)
In this segment the emphasis is on brand experience, storytelling, branding and the retail environment, such as specialised coffee shops and premium branding. Consumers pay significantly higher prices. This segment is under pressure, mainly due to pricing. Some consumers shift from this segment to entry-level specialty coffee.
High-end specialty coffee (cupping scores 89+)
This smaller but prestigious segment focuses on exceptionally high quality, unique flavour profiles, transparency of origin, and direct relationships with specific farms. These coffees are often sold in specialised cafés or through direct online channels and achieve the highest retail prices. While some producers receive higher price shares, outcomes are highly heterogeneous and depend on specific relationships and business strategies. Often, these coffees are graded 89+. This segment is growing, particularly in France, Spain and Eastern Europe.
Certified specialty coffee (cross-cutting segment)
Certifications such as Fairtrade, organic and Rainforest Alliance do not constitute a separate quality segment but overlap with other specialty categories. They differentiate products based on ethical and environmental attributes.
Overall, certification is less important in the specialty coffee segment. Certification primarily signals that a product meets minimum standards, whereas specialty coffee is defined by exceeding those standards. Also, one of the main incentives for certification is the price premium it can generate. However, specialty coffee producers often already receive higher prices due to superior quality. Within the specialty segment, organic certification tends to be more relevant than other certification schemes.
Figure 4: Coffee end-market segmentation
Source: input based on multiple sources, figure generated by ChatGPT
Tips:
- Know the coffee you sell. This includes information on where it is grown, processing, quality and grading, as well as flavour attributes. This can help you to sell your coffee at a higher price, based on its quality profile and market demand.
- Become a Q grader to properly assess your own coffee.
Through which channels does speciality coffee land on the end market?
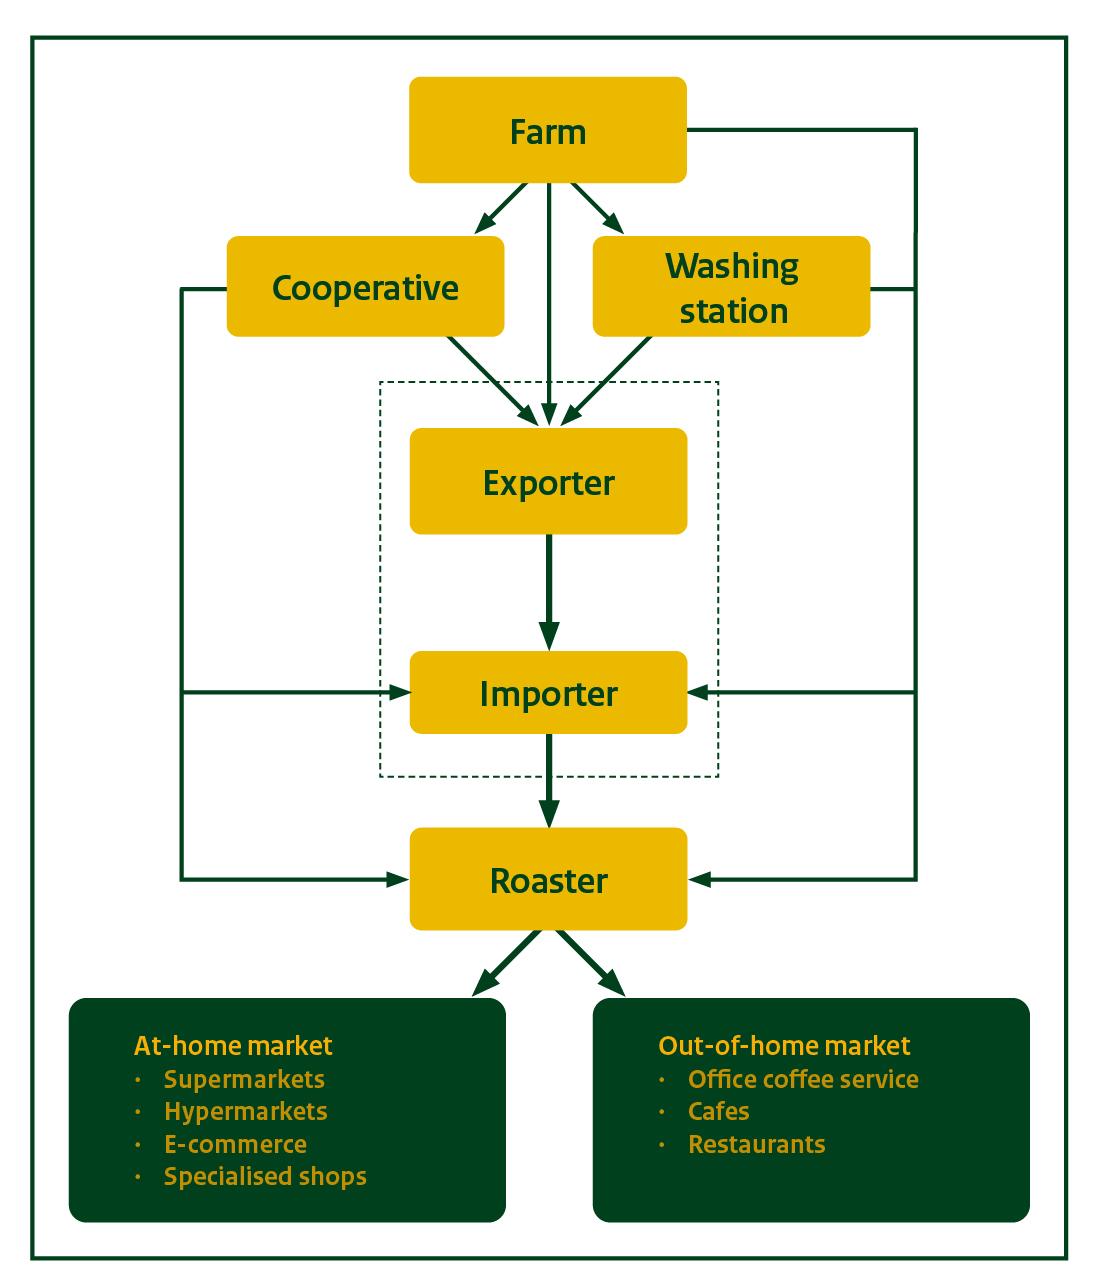
Most entry-level specialty coffee follows the same market channels as conventional coffee. Coffee in this segment usually follows all steps of the value chain. In higher segments, the speciality value chain can be more transparent and shorter than in the commodity value chain.
Producers sometimes sell their speciality coffee directly to specialised importers or small-scale roasters. This may increase efficiency and distributes prices more fairly, although it usually requires high investments in marketing and sales.
Figure 5: The specialty coffee supply chain
Source: based on Counter Culture Coffee
Importers are the main buyers
Importers play a vital role in the coffee market. They act as supply-chain managers and maintain extensive portfolios with various origins. They also handle logistics, provide pre-finance operations, perform quality control, and manage price fluctuations. Importers also establish contact between producers and buyers, such as roasters. Usually, importers have long-standing relationships with their suppliers and customers.
At record Arabica prices in 2024–2025 (peaking at US$4.41/lb in February 2025), importers faced strong margin pressure. Smaller independent importers were hit hardest, and some left the market. As a result, reliable, consistent supply from trusted origin partners has become more valuable than ever.
Specialised importers can buy small volumes of high-quality or single-origin coffees. Among small and large specialised importers in Europe are:
- Cafe Imports Europe, Rehm & Co and Touton Specialties Coffee (Germany);
- Trabocca, The Coffee Quest and This Side Up (Netherlands);
- Belco (France);
- Sucafina Specialty (Belgium);
- Falcon Coffees (UK);
- Imperator (Italy).
Small roasters offer a great opportunity for direct trade
Small roasters often source green coffee from importers. This is easier than sourcing from producers directly, as it relieves small-scale roasters of tasks outside their core expertise. Importers can also guarantee traceability, which is essential for roasters to share the backstory with customers.
The number of small roasters importing from origin is growing, though the share is still small. Small roasters often specialise in high-quality blends and single origins. They usually perform cup tests to check the evenness of the roast. This also helps them spot defects that can occur post-harvest. Post-harvest defects can happen during fermentation, drying or storage. Small roasters trading directly with producers are generally less interested in certification. Instead, they have their own ways of assessing sustainability and quality. Small roasters sourcing coffee directly from producing countries include:
- Coffee Station (Netherlands);
- Frekko (Belgium);
- Günter Coffee (Germany);
- Solberg & Hansen (Norway);
- Coffee Collective (Denmark);
- Iron & Fire (UK).
Online marketplaces facilitate trade
The European coffee market is slowly changing. Some farmers and cooperatives have direct relations with roasters, which gives roasters more control and transparency. In some cases, roasters also take steps to shorten the supply chain. Illy Caffè, for instance, is one of Italy's best-known coffee companies and works directly with farmers. Most of its coffee, however, still comes from large trading companies.
Online marketplaces are helping to facilitate this change and promote direct trade. Marketplaces are platforms that connect actors in the chain, mainly connecting farmers to roasters directly. Using marketplaces allows farmers, cooperatives or washing stations to cut out parts of the chain. This may allow you to increase profits and to tell the story about your coffee. Some of these marketplaces are:
Although these marketplaces initially focused on specialty coffee, they are now used more and more by conventional coffee traders too. Online marketplaces are rarely used as a sole sales channel; instead, they serve to diversify market channels and help sellers reach new buyers.
Moreover, these platforms can provide a first step towards engaging in direct trade. Beyond the online marketplace itself, they offer support and guidance in establishing business relationships. Algrano also provides education to help producers prepare for exporting their products. Both Beyco and Algrano can additionally assist producers with pre-financing.
Tips:
- Consider selling your coffee via online marketplaces like Algrano, Raw Material or Beyco. You can start with small batches, which can help diversify your market channels.
- Read our tips to organise your export to learn about the basics of starting to export abroad.
What is the most interesting channel for you?
The most interesting market channel for specialty coffee depends strongly on your specific context, including your quality level, volumes, story, and capacity to engage beyond spot transactions. For most exporters, specialised importers are the most realistic channel and the lowest-risk entry point, provided you can demonstrate consistent quality and a long-term relationship.
Specialised traders typically operate in differentiated specialty segments. Entry into these channels usually requires verifiable cupping scores of at least 80 points. However, many buyers set higher thresholds of 85 or above, particularly for single‑origin and micro‑lot coffees. These buyers often seek distinctive flavour profiles, consistency over time and clear traceability.
Many specialised importers prefer working directly with producers or organised cooperatives, as this enables closer quality control, storytelling and transparency. Direct or semi‑direct relationships can also reduce information asymmetries and create space for dialogue about pricing, quality investments and risk sharing.
Tips:
- Look for business partners that are beneficial in the long term. Usually, these are the business partners that have your interest at stake and are willing to engage in long-term relationships.
- Read our tips to find buyers for more information on how to find new buyers and create better market access.
3. What competition do you face on the speciality coffee market?
As a coffee supplier you operate in a global and competitive landscape. As a producer or exporter, it is important to understand the market segment you operate in and the scale at which you work. By identifying these factors, this helps you find out which countries compete with you. Understanding the quality level, volume and positioning of your products allows you to better assess your competition and develop strategies to differentiate yourself in the global market. This knowledge is essential for competing more effectively and standing out in the market.
Which countries are you competing with?
The speciality segment focuses on quality, origin, sustainability and long-term direct trade relations. Yearly competitions identify the highest quality coffees produced worldwide. It is important to consider the producing country's government policies influencing the coffee sector. These policies can have an impact on the opportunities and development of the sector.
Data on exporting numbers in the specialty coffee segment are lacking. However, some countries are famous for specialty coffee and their large contribution to the European market. This section describes the four countries that are major exporters of specialty coffee.
Brazil: World's largest coffee supplier
Brazil is the world's largest coffee producer and a prominent speciality supplier. It is also the world's largest coffee producer and Europe's largest supplier. Brazil produces both Arabica (70%) and Robusta (30%).
Brazilian coffee is most commonly known for its low acidity and smooth feel and taste. Cupping experts usually find hints of caramel, chocolate or nutty flavours. However, the taste profile depends on various factors like coffee varieties. Mundo Novo, Bourbon, Catuaí and Acaiá are the most common coffee varieties. Brazil is mostly known to dry-process their coffee due to the climate's dry seasons.
Almost 73% of Brazilian coffee is harvested partially with machines. The flat Brazilian landscape allows machines to harvest more easily, making the process more efficient. Mechanised harvest is usually not suitable for specialty coffee. For specialty coffee, it is crucial only to pick ripe cherries. Plucking machines are generally unsuitable for distinguishing between ripe and unripe cherries.
Nevertheless, Brazil has established itself as a trusted specialty supplier. This is in part thanks to the Brazil Specialty Coffee Association (BSCA), which aims to elevate the quality standards and enhance the value of Brazilian coffees.
Brazil is one of the countries hosting the annual Cup of Excellence competition. The aim of the competition is to identify the highest quality coffees produced. Rewarded coffees are sold in global online auctions at premium prices. The competition is organised by the Alliance for Coffee Excellence.
Bourbon Specialty Coffees is a Brazilian producer that focuses on sustainable farming practices. They especially value a direct relationship with farmers. This commitment to quality and sustainability has helped them become a reputable exporter. They invest in research and development about varieties, picking and processing, which helps discover how they can improve performance.
Table 1: Competitive country profile of Brazil
| Strengths | Weaknesses | Image on the coffee market |
|---|---|---|
|
|
|
Colombia: Strong country brand
Colombia is the world's third-largest coffee producer, after Brazil and Vietnam. In 2025, Europe imported 228,000 tonnes of green coffee from Colombia. Imports from Colombia fluctuate year by year due to changing production volumes. Although European import levels from Colombia vary, there is no clear upward or downward trend. For 2026, lower imports are expected due to a 7% decrease in production.
Colombia is the world's largest producer of washed Arabica. It has a strong coffee industry with advanced technological development. The country has an established image and brand for high-quality coffees. Colombian coffee is known for its chocolate, nuts, herbs, fruit and citrus notes. Its main processing technique is washed. The country's most well-known coffee varieties include Typica, Bourbon, Caturra and Castillo.
The Colombian Coffee Growers Federation strategically promotes and markets Colombian coffee. Café de Colombia is a protected trademark, and is registered in eAmbrosia, the register for protected trademarks in Europe. A registration in eAmbrosia is unique among coffee-producing countries, and it protects the rights of more than 550,000 small-holder families in the country.
The Colombian coffee industry is constantly developing. Coffee companies are more and more involved in capacity building and product quality. Colombian producers can follow coffee quality and tasting programmes to get certified.
The country's coffee has ongoing success in competitions, such as the World Barista Championships. La Meseta is a Fairtrade- and organic-certified producer and exporter of specialty and conventional coffee. They focus on sustainable agriculture, including shade-grown coffee, organic farming methods and eco-friendly processing techniques.
Table 2: Competitive country profile of Colombia
| Strengths | Weaknesses | Image on the coffee market |
|---|---|---|
|
|
|
Ethiopia: Among the world's leading organic coffee producers
Ethiopia is one of the world's leading organic coffee producers; 95% of its produced coffee is organic, mainly due to a lack of money. Most farmers do not have the money to buy any agricultural inputs. This also results in a very low production. Ethiopian coffee is mostly known for its fruity and floral flavour profile. Their most common processing techniques are sun drying and wet washing. The most common varieties include Longberry, Shortberry and Mocha.
Ethiopia is often seen as the birthplace of coffee. This is because many coffee varieties can be traced back to Ethiopian forest grounds. Climate change experts have found that climate fluctuations in Ethiopia are likely to occur more often. This will reduce the land available for the production of specialty coffee. The Ethiopian government encourages the sector to adopt more sustainable growing techniques.
Ethiopian coffee is known for its taste, quality and origin. The Ethiopian coffee market is highly fragmented and competitive. Ethiopia's coffees have high potential in the speciality market. Their economy benefits greatly from their coffee export. This is why the country's government prioritises policies that safeguard social, economic and environmental sustainability.
Bette Buna is an example of a producer and exporter that invests in the local community by creating job opportunities for young adults and giving financial trainings to their employees. They also have four coffee breeding nurseries to provide resilient coffee varieties that boost quality. Moyeefocuses on providing single-origin coffee, but also offers specialty blends; they roast at origin and export their roasted coffee to Europe, so a higher share of the added value flows to Ethiopia.
Table 3: Competitive country profile of Ethiopia
| Strengths | Weaknesses | Image on the coffee market |
|---|---|---|
|
|
|
Kenya's coffee exchange: Offering better prices for farmers
Kenya's grading system makes it easy to source high-quality coffee. Kenya's coffee industry is organised around coffee auctions by the Nairobi Coffee Exchange (NCE), a government-owned, not-for-profit organisation. At the auction, lots with higher quality coffee are sold for higher prices. This system benefits international market prices for Kenyan coffee but limits opportunities for Kenyan producers to trade with international actors directly. Kenya's Coffee Producers Association(KCPA) represents almost 350,000 coffee-producing households to empower them to address issues related to production, processing and marketing.
Kenyan coffee is rated high for its vibrant and crisp citrus, pepper and blackberry flavours. The washed processing technique is the most common processing method.
Gikanda Coffee is Rainforest Alliance-, organic- and Fairtrade-certified. They experiment with different coffee processing methods. For example, they have experience with anaerobic fermentation and controlled drying processes. The cooperative invests in the community's health care access and education. Othaya Coffee is another Kenyan coffee producer with Fairtrade certification; they give a sustainable income to around 1100 small-scale farmers.
Table 4: Competitive country profile of Kenya
| Strengths | Weaknesses | Image on the coffee market |
|---|---|---|
|
|
|
Tips:
- Identify and promote your unique selling points. Give detailed information about your coffee-growing region or origin and the varieties, qualities, post-harvesting techniques and certification of the coffee you offer. You can also tell the history of your organisation, your coffee-growing farm, and the passion and dedication of the people working there. These are all elements that make your company unique.
- Actively promote your company on your website and in trade fairs. Flavour quality competitions also provide good opportunities to share your story. In 2027, World of Coffee 2027 will take place in locations like Bogota, Colombia.
- Develop long-term partnerships with your buyers by consistently meeting their requirements and keeping your promises. This will give you a competitive advantage, more knowledge and stability in the European market. Read Trabocca's article on understanding your coffee contract. This ensures you have documented the agreement with your buyer.
Molgo Research carried out this study in partnership with Ethos Agriculture on behalf of CBI.
Please review our market information disclaimer.
Search
Enter search terms to find market research
Do you have questions about this research?
Build relationships and own your value chain. This offers you more direct feedback, committed buyers and ownership over your product."
John Gibson, head of sourcing at The Coffee Collective
Webinar recording
19 May 2022 Exporting Specialty Coffee to Europe